


Related articles

Medicare Plans in Wilmington, NC for 2027: New Hanover County Guide
Compare Medicare plans in Wilmington, NC for 2027: 37 Medicare Advantage plans in New Hanover County, how NC Medigap pricing works and what to check by Dec. 7.
Read More
Medicare Plans in Myrtle Beach, SC for 2027: Horry County Guide
Compare Medicare plans in Myrtle Beach, SC for 2027: 41 Medicare Advantage plans in Horry County, Medigap basics and what to check before Dec. 7.
Read More
Marketplace to Medicare at 65: When to Switch (SC, NC, GA)
Marketplace to Medicare at 65: end your plan the day before Medicare starts, expect subsidies to stop and avoid a Part B penalty. SC, NC and GA rules.
Read More
Medicare Initial Enrollment Period: Your 7-Month Window Explained
The Medicare Initial Enrollment Period is a 7-month window around your 65th birthday. See start dates, a worked example and the penalty for missing it.
Read More
Medicare Plans in Augusta, GA for 2027: Richmond County Guide
Compare Medicare plans in Augusta, GA for 2027: 50 Medicare Advantage plans in Richmond County, Medigap basics and what to check before Dec. 7.
Read More
Medicare Plans in Columbia, SC for 2027: Richland County Guide
Compare Medicare plans in Columbia, SC for 2027: 39 Medicare Advantage plans in Richland County, Medigap basics and what to check before Dec. 7.
Read More
TRICARE For Life and Medicare in North Carolina and Georgia
TRICARE For Life and Medicare in North Carolina and Georgia: why Part B is required, who pays first and how Medicare Advantage fits. Know before you sign up.
Read More
Medicare Plans in Asheville, NC for 2027: What to Compare
Compare Medicare plans in Asheville, NC for 2027: 44 Medicare Advantage plans in Buncombe County, Medigap basics, and what to check before Dec. 7.
Read More
Medicare Plans in Greenville, SC for 2027: What to Compare
Compare Medicare plans in Greenville, SC for 2027: 51 Medicare Advantage plans in Greenville County, Medigap basics, and what to check before Dec. 7.
Read More
Can You Keep Your Medigap Plan If You Move to Another State?
Can you keep your Medigap plan if you move to another state? Usually yes with Original Medicare. See when to switch, health questions and SC, NC, GA help.
Read More
Medicare Plans in Atlanta, GA for 2027: Compare by County
Compare Medicare plans in Atlanta, GA for 2027: Medicare Advantage plan counts in 5 metro counties, Medigap basics and what to check before Dec. 7.
Read More
What Happens If You Do Nothing During Medicare Open Enrollment? (2027)
What happens if you do nothing during Medicare open enrollment? See what carries into 2027, what can change on Jan. 1, and what to check by Dec. 7.
Read More
NC State Health Plan Retirees and Medicare: 2027 Changes
NC State Health Plan retirees with Medicare: 2027 cost changes to the Humana plans, the Nov. 6 open enrollment deadline, and what your options are.
Read More
Medicare Plans in Charleston, SC for 2027: What to Compare
Compare Medicare plans in Charleston, SC for 2027: 46 Medicare Advantage plans in Charleston County, Medigap basics, and what to check before Dec. 7.
Read More
Medicare Advantage Plans in North Carolina for 2027: What to Check
Compare Medicare Advantage plans in North Carolina for 2027: what changed, how your county sets your options, and what to check before the Dec. 7 deadline.
Read More
Bluffton and Hilton Head Island Real Estate: Why Buyers Are Moving to the Lowcountry, and Why Andy Thompson Is the Advisor to Call
Why buyers from the Northeast, the Midwest and beyond keep choosing Bluffton and Hilton Head Island, and why Realty ONE Group Lowcountry's Andy Thompson is a strong local advisor.
Read More
Medicare Plans in Raleigh, NC for 2027: Wake County Guide
Compare Medicare plans in Raleigh, NC for 2027: Medicare Advantage vs Medigap, how North Carolina pricing works, and what to do before the Dec. 7 deadline.
Read More
Medicare Advantage Plans in Georgia for 2027: What to Check
Compare Medicare Advantage plans in Georgia for 2027: statewide numbers, what changes by county, how to switch, and the Dec. 7 deadline, with no-cost help.
Read More
Medicare Advantage Plans in South Carolina for 2027: What to Check
Compare Medicare Advantage plans in South Carolina for 2027: the key numbers, how your county decides your options, and the Dec. 7 deadline, with no-cost help.
Read More
Spanish-Speaking Medicare Agent in SC, NC and GA
Looking for a Spanish-speaking Medicare agent in SC, NC or GA? See your options for Medicare help en español, including phone lines and enrollment dates.
Read More
Medicare Extra Help: 2026 Income Limits and 2027 Drug Costs
Medicare Extra Help can cut your Part D costs. See the 2026 income and resource limits, the 2027 drug copays, and how to apply in SC, NC and GA.
Read More
Medicare Plans in Charlotte, NC for 2027: What to Compare
Compare Medicare plans in Charlotte, NC for 2027: what is changing, Medicare Advantage vs Medigap, and what to check before open enrollment ends Dec 7.
Read More
Can You Be Denied Medigap? SC, NC and GA Rules (2026)
Can you be denied Medigap? Yes, outside protected windows. See when SC, NC and GA residents have a right to a policy and when health answers matter.
Read More
Georgia Medicare Savings Programs 2026: QMB, SLMB and QI
Georgia Medicare Savings Programs in 2026: QMB, SLMB and QI income limits, what each pays and how to apply through DFCS to cut your Part B premium.
Read More
SC State Retiree Health Insurance and Medicare: What PEBA Retirees Do
South Carolina state retiree health insurance and Medicare: how PEBA's Medicare Supplemental Plan works, the 31-day deadline, Part B and your drug plan.
Read More
Turning 65 in 2027: Your Medicare Enrollment Dates by Month
Turning 65 in 2027? See your Medicare enrollment window by birth month, when coverage starts and the penalty for missing it, for readers in SC, NC and GA.
Read More
Medicare Advantage Plan Ending in 2027? What to Do Next
Medicare Advantage plan ending in 2027? Learn the Dec 7 and end-of-February deadlines, your Medigap window and what to do if you do nothing in SC, NC and GA.
Read More
Medicare Agent in Bluffton, SC: How to Choose One and What to Ask
Looking for a Medicare agent in Bluffton, SC? See how to verify a license, what to ask, and what to bring so you can compare plans at your address.
Read More
COBRA and Medicare: Do You Still Need Part B After You Retire?
COBRA and Medicare do not work like active job coverage. See the 8-month Part B window, the 10% penalty and a retirement checklist for SC, NC and GA.
Read More
Medigap Plan G vs Plan N: Cost, Copays and Who Each Fits (2027)
Medigap Plan G vs Plan N explained: what each covers, Plan N's $20 and $50 copays, excess charges, and a worked cost example for SC, NC and GA.
Read More
Medigap Open Enrollment Period: Your 6-Month Window (SC, NC, GA)
The Medigap open enrollment period gives you 6 months to buy a Medicare Supplement without health questions. See dates, examples and rules for SC, NC, GA.
Read MoreDo Medicare Agents Charge a Fee? How They Get Paid
Do Medicare agents charge a fee? See who pays them, the rules that protect you, and what to ask before you enroll in South Carolina, North Carolina or Georgia.
Read More
Medicare Supplement vs Medicare Advantage in South Carolina (2027)
Medicare Supplement vs Medicare Advantage in South Carolina: how doctors, costs, drugs and switching rules differ, plus a checklist before Dec 7.
Read More
Medicare Late Enrollment Penalty: Part B and Part D in 2027
Medicare late enrollment penalty explained: Part B adds 10% per year, Part D adds 1% a month. See 2027 examples, how to avoid it and who gets exceptions.
Read More
Switch Medigap Plans in SC, NC and GA: What the Rules Allow
Can you switch Medigap plans in SC, NC or GA? Learn the federal rules, why none of the three has a birthday rule, and what to check before you cancel.
Read More
Part D Plans in Georgia 2027: Costs, Changes and How to Compare
Part D plans in Georgia 2027: see the $2,400 drug cap, fewer plans, no $0 premiums without Extra Help, and how to compare before the Dec 7 deadline.
Read More
Turning 65 in South Carolina: Your Medicare Enrollment Guide
Turning 65 in South Carolina? See when to sign up for Medicare, how the 7-month window works, Part B penalty rules and your Medigap and Advantage options.
Read More
Medicare Supplement vs Medicare Advantage in North Carolina (2027)
Medicare Supplement vs Medicare Advantage in North Carolina: how each works, what changes in 2027, when you can switch and questions to ask first.
Read More
Part D Plans in South Carolina 2027: Costs and What Changed
Part D plans in South Carolina for 2027: the new $2,400 cap, fewer stand-alone plans, no $0 premiums without Extra Help and how to compare before Dec 7.
Read More
Medicare Advantage Open Enrollment Period 2027: Jan 1 to Mar 31
Medicare Advantage Open Enrollment Period 2027 runs Jan 1 to Mar 31. See who qualifies, the one change you can make and how to switch or go back to Original.
Read More
Medigap Plan G in Georgia: Cost and How to Compare (2027)
Medigap Plan G in Georgia: what it covers, what rates look like, how Georgia limits age-based pricing and when you can switch. Compare options by address.
Read More
Medigap Plan G in North Carolina: Cost and How to Compare (2027)
Medigap Plan G in North Carolina: what it covers, why rates differ by insurer, how attained-age pricing works and when you can switch. Compare by address.
Read More
Medicare Plans in Savannah, GA for 2027: What to Compare
Compare Medicare plans in Savannah, GA for 2027: Medigap vs Advantage, Georgia rules, the Dec. 7 deadline and what to bring for a no-cost plan comparison.
Read More
Part D Plans in North Carolina 2027: Premiums and Deductibles
Part D plans in North Carolina 2027: 11 standalone plans, premiums from $5.30 to $239.20, a $700 deductible cap and how to compare them by Dec. 7.
Read More
Moving to North Carolina With Medicare: What to Do First (2027)
Moving to North Carolina with Medicare? See what happens to Original Medicare, Advantage, Medigap and Part D, plus the special enrollment timing.
Read More
Working Past 65 and Medicare: When to Sign Up for Part B
Working past 65 and Medicare: when you can delay Part B, the 8-month window after work ends, the 10% penalty and the Medigap clock. For SC, NC and GA.
Read More
Moving to Georgia With Medicare: What to Do First (2027)
Moving to Georgia with Medicare? See what happens to Original Medicare, Medigap, Advantage and Part D, the special enrollment timing and Georgia rules.
Read More
Medigap Plan G in South Carolina: Cost and How to Compare (2027)
Medigap Plan G in South Carolina: what it covers, why prices vary by insurer, how age rating works and when you can switch. Compare 2027 options by address.
Read More
Turning 65 in Georgia: Your Medicare Enrollment Guide
Turning 65 in Georgia? See when to sign up for Medicare, how Part B timing works, what Georgia adds for Medigap, and a worked example with exact dates.
Read More
Switch From Medicare Advantage to Medigap in SC, NC and GA
Thinking of switching from Medicare Advantage to Medigap? See when insurers must accept you, when they can ask health questions, and SC, NC and GA differences.
Read More
How to Switch Medicare Plans During Open Enrollment (2027)
Want to switch Medicare plans during open enrollment? See what you can change before December 7, the steps to follow, and what to do if you miss the deadline.
Read More
Moving to South Carolina With Medicare: What to Do First
Moving to South Carolina with Medicare? Learn what happens to Original Medicare, Advantage, Medigap and Part D, and your 2-month window to switch.
Read More
Turning 65 in North Carolina: Your Medicare Enrollment Guide
Turning 65 in North Carolina? See when to sign up for Medicare, how Part B timing works, and your six-month Medigap window, with a worked example.
Read More
Medicare Supplement vs Medicare Advantage in Georgia (2027)
Medicare Supplement vs Medicare Advantage in Georgia: how each works, what each costs you, and a five-question checklist to decide before December 7.
Read More
Medicare Dental Coverage Near Sun City Hilton Head: What Plans Pay and Nearby Dental Offices
Original Medicare skips routine dental. Here is what some Medicare Advantage plans add in Beaufort and Jasper counties for 2027, plus five dental offices near Sun City and what to ask before you book.
Read More
Sun City Hilton Head by the Numbers: What an 18,000-Resident 55+ Community Means for Medicare
From 100 first residents in 1995 to more than 18,000 today, the key numbers behind Sun City Hilton Head and the Medicare questions that follow.
Read More
Fitness, Wellness and Medicare Near Sun City Hilton Head
Sun City Hilton Head is built around an active lifestyle. Here is how Medicare plans handle fitness and wellness benefits, and what to verify first.
Read More
Moving to Sun City Hilton Head: Your Medicare Checklist
Relocating to Sun City Hilton Head? Here is what to do about Medicare, from Special Enrollment Periods to avoiding late-enrollment penalties.
Read More
Part-Time Residents of Sun City Hilton Head: How Medicare Works When You Split the Year
Snowbirds and seasonal residents: how plan service areas, networks and enrollment windows affect Medicare when you live in two places.
Read More
Medicare Advantage vs. Medigap for Active Retirees in Sun City Hilton Head
Active, travelling retirees weigh low premiums against flexibility. Here is how Medicare Advantage and Medigap compare, with the latest enrollment data.
Read More
Doctors and Hospitals Near Sun City Hilton Head: What to Check Before Choosing a Medicare Plan
Hospitals and care sites near Sun City Hilton Head, how far the big academic centers are, and why your doctors should decide your Medicare plan.
Read More
Turning 65 in Sun City Hilton Head? Your Medicare Timeline
Moving to Sun City at 55 is common. Medicare starts at 65, and missing your window can cost you for life. Here is the timeline for Sun City residents.
Read More
2027 Medicare Plan Changes for Sun City Hilton Head Residents
BlueCross Total PPO is leaving Beaufort County for 2027, and plan choices are shrinking nationwide. Here is what Sun City Hilton Head residents should check before December 7.
Read More
Sun City Hilton Head Sits in Two Counties. Why Neighbors Can Have Different Medicare Plans
Sun City sits between Beaufort and Jasper counties, and Medicare plans are sold by county. Here is why two neighbors can see different options, using BlueCross's 2027 plans as an example.
Read More
Medicare in Sun City Hilton Head: The Complete Guide for Residents
Sun City Hilton Head has more than 18,000 residents in a 55+ community near Bluffton and Okatie. Here is how Medicare works for Sun City residents, from enrollment dates to plan choices.
Read More
Who Sells Medicare Advantage? UnitedHealthcare and Humana Hold 46% of the Market
35.2 million people are in Medicare Advantage in 2026, and two companies cover nearly half of them. Here is the market share breakdown and what it means for choosing a plan.
Read More
South Carolina Medicare Savings Programs in 2026: Income Limits and How to Apply
South Carolina residents with limited income may get help paying Medicare premiums through QMB, SLMB, and QI. Here are the 2026 limits and where to apply.
Read More
Medicare IRMAA in 2026: Income Brackets and What High Earners Pay for Part B
If your income is above $109,000 (single) or $218,000 (married filing jointly), you pay more for Medicare Part B. Here are the 2026 IRMAA brackets and how to appeal.
Read More
Medicare Part B Premium and Deductible: 2026 Costs and the 2027 Outlook
The 2026 Part B premium is $202.90 a month with a $283 deductible. The 2027 amounts are not final yet. Here is what you pay now and what the Trustees project.
Read More
Medicare and TRICARE For Life in Beaufort, SC: What Military Retirees Should Know
Beaufort is home to Parris Island, MCAS Beaufort, and a naval hospital. If you are a military retiree, here is how Medicare and TRICARE For Life fit together and what to check before you change plans.
Read More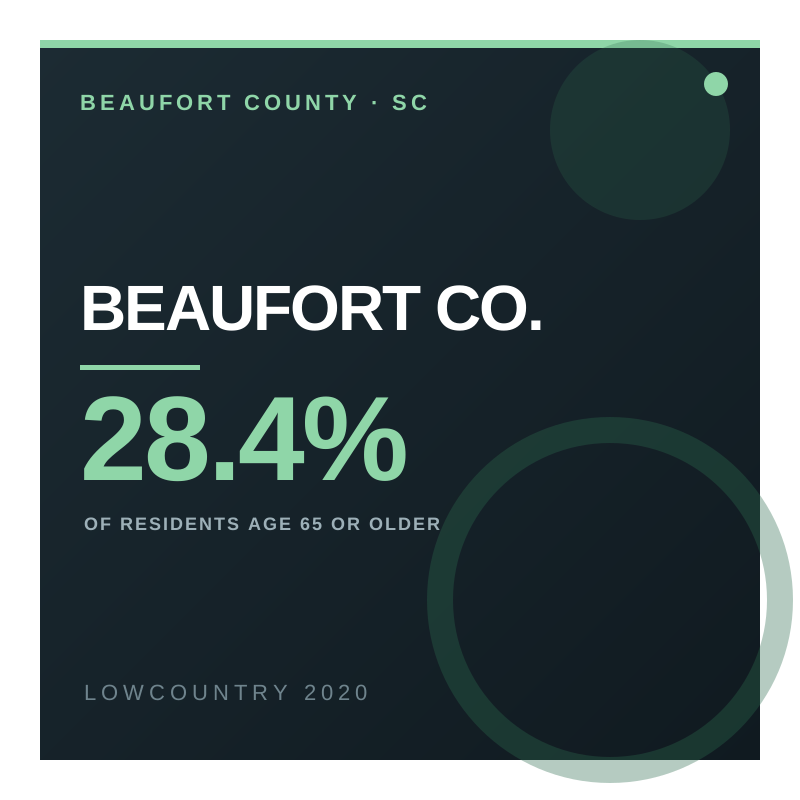
Medicare in Beaufort County, SC: Plans, Enrollment, and Free Help
More than 28% of Beaufort County residents are 65 or older. Here is how Medicare works in the county, what is changing for 2027, and where to get free help.
Read More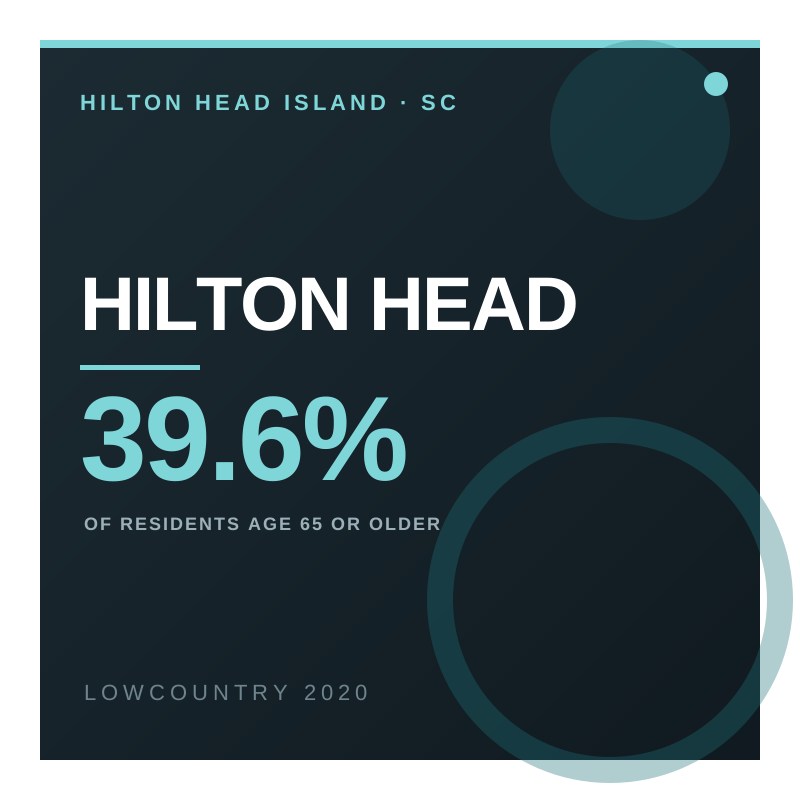
Medicare on Hilton Head Island: A Guide for Retirees and Seasonal Residents
Nearly 40% of Hilton Head Island residents are 65 or older. Here is how Medicare works for year-round and seasonal residents, and what to check about doctors and plan networks.
Read More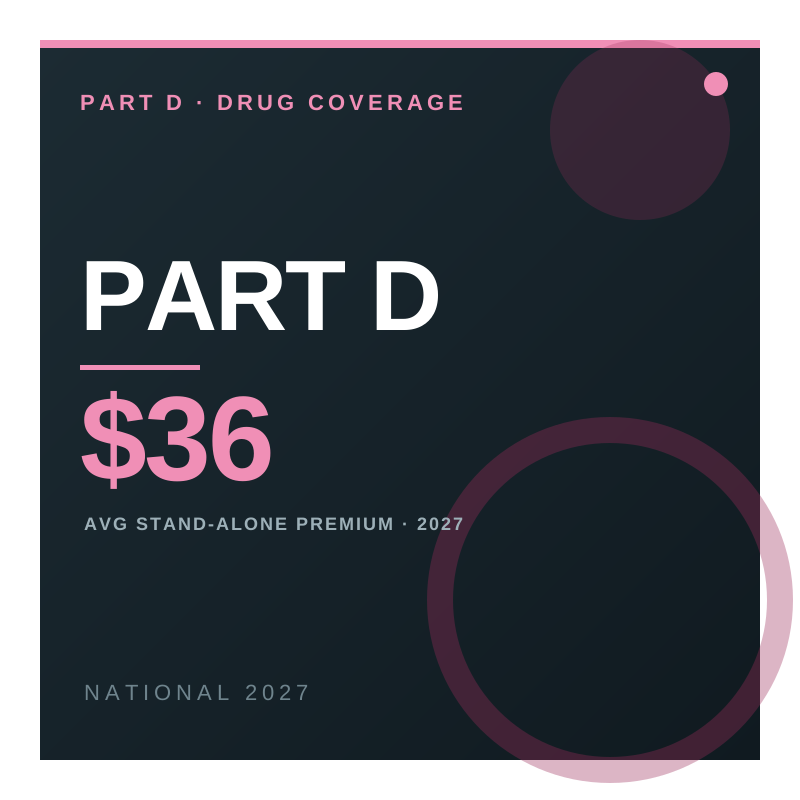
Medicare Part D in 2027: Average Premiums, Costs, and the Drug Cap
The average stand-alone Part D premium is $36 in 2027, while the Part D premium inside Medicare Advantage plans falls to $7. Here is how the numbers compare and what to check.
Read More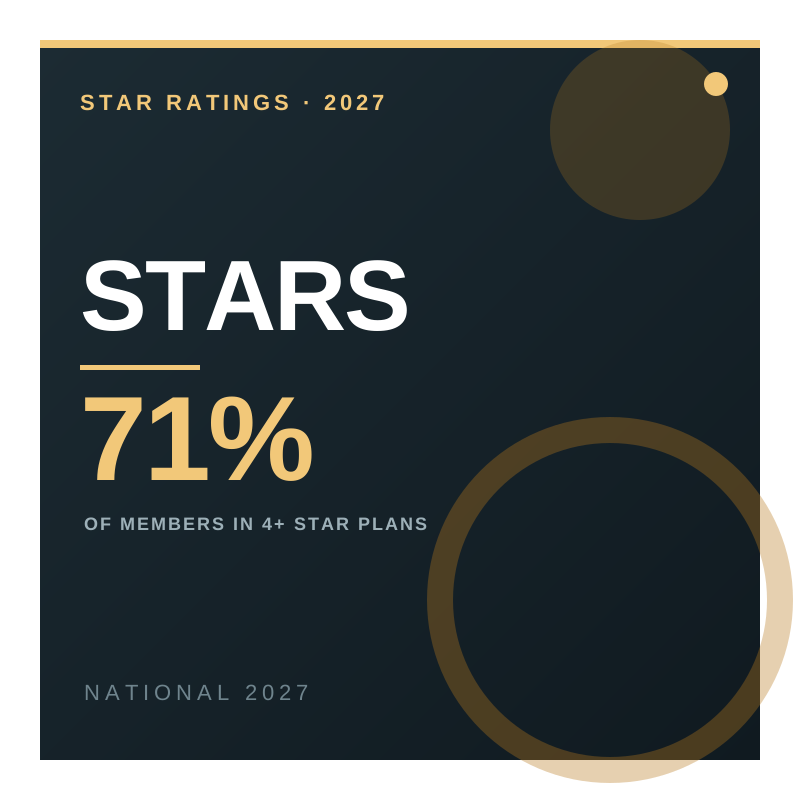
2027 Medicare Advantage Star Ratings: 71% of Members Are in 4-Star Plans or Better
CMS released 2027 star ratings on October 8, 2026. About 71% of Medicare Advantage drug plan members are in plans rated 4 stars or higher. Here is what the ratings mean and how to use them.
Read More
Medicare Advantage in 2027: Average Premium Falls to $12, but You Have Fewer Plans
CMS says the average Medicare Advantage premium drops to $12.00 in 2027, but the typical person will see fewer plans to choose from. Here is what changed and what to check.
Read More
BlueCross BlueShield of South Carolina Is Changing 7 Medicare Plans for 2027
Seven BlueCross BlueShield of South Carolina Medicare plans are ending or shrinking their service areas for 2027, affecting more than 19,000 members.
Read More
Medicare Enrollment Dates for 2027 Coverage: What to Do and When
Annual Enrollment, the January to March window, and the special period for people whose plan is ending. Here are the Medicare dates that matter for 2027 coverage.
Read MorePreventive vs. Comprehensive Dental in Medicare Advantage: What to Know in Beaufort County
Original Medicare generally leaves out routine dental. Here is the difference between preventive and comprehensive dental in Medicare Advantage, and how BlueCross's 2027 Beaufort plans compare.
Read More
BlueCross Total PPO Is Leaving Beaufort County in 2027. What Members Should Do
BlueCross BlueShield of South Carolina is pulling its Total PPO from Beaufort and Charleston counties for 2027. Here is the timeline and your options.
Read More
Turning 65 in Bluffton, SC? Your Medicare Timeline and What Is Changing for 2027
Turning 65 or reviewing your plan in Bluffton, SC? Enrollment windows, 2027 plan changes, nearby hospitals and free local help, all in one guide.
Read More
Data & Methodology
Every dataset behind our county, city, and ZIP code pages — what it measures, where it comes from, and how it's cited.
Read More
Shingles and RSV Vaccines on Medicare in South Carolina: $78 Million Spent in 2023, $0 for You
South Carolina Medicare spent $78 million on Shingrix and Arexvy in 2023. Part D covers CDC-recommended adult vaccines with no copay. Here is who should ask about each and how to get them.
Read More
Shingles and RSV Vaccines on Medicare in North Carolina: $91 Million Spent in 2023, $0 for You
North Carolina Medicare spent $91 million on Shingrix and Arexvy in 2023. Part D covers CDC-recommended adult vaccines with no copay. Here is who should ask about each and how to get them.
Read More
Mounjaro on Medicare in North Carolina: $86 Million in 2023 and Where Costs Are Headed
Mounjaro cost North Carolina Medicare $86 million in 2023, its first full year. Here is how tirzepatide is covered today, what changed in 2026, and what to check before December 7.
Read More
Biktarvy on Medicare in North Carolina: $122 Million in 2023 and What Comes Next
Biktarvy was North Carolina's tenth most expensive Medicare Part D drug in 2023 at $122 million. It is now headed into Medicare price negotiation. Here is what that means for you.
Read More
Ozempic on Medicare in South Carolina: $176 Million in 2023 and the 2027 Negotiated Price
Ozempic was South Carolina's second most expensive Medicare Part D drug in 2023 at $176 million. Medicare's negotiated price starts in 2027. Here is what that means for you.
Read More
Ozempic on Medicare in North Carolina: $407 Million in 2023 and the 2027 Negotiated Price
Ozempic was North Carolina's second most expensive Medicare Part D drug in 2023 at $407 million. Medicare's negotiated price starts in 2027. Here is what that means for you.
Read More
Eliquis (Apixaban) on Medicare in South Carolina: $321 Million in 2023 and the 2026 Price Cut
Eliquis was South Carolina's costliest Medicare Part D drug in 2023 at $321 million. Medicare's negotiated price took effect in 2026. Here is what changed and how to check your own cost.
Read More
Eliquis (Apixaban) on Medicare in North Carolina: $689 Million in 2023 and the 2026 Price Cut
Eliquis was North Carolina's costliest Medicare Part D drug in 2023 at $689 million, about 1.7 times the next-highest drug. Medicare's negotiated price took effect in 2026. Here is what changed.
Read More

